










Most people hunt for the APR in a card agreement and stop there. The minimum interest charge line is easy to miss, and the sources behind this piece are thin on it. So this guide covers what can be confirmed, what cannot, and how to read the surrounding terms that decide what borrowing really costs.
What the minimum interest charge line is and where it comes from
The minimum interest charge is a disclosure tied to federal rules for open-end credit, which is the category credit cards fall into. Under Regulation Z, the threshold that triggers the requirement to disclose a minimum interest charge stayed at $1.00 for 2024, unchanged from the prior level. That is the one firm number the research supports.
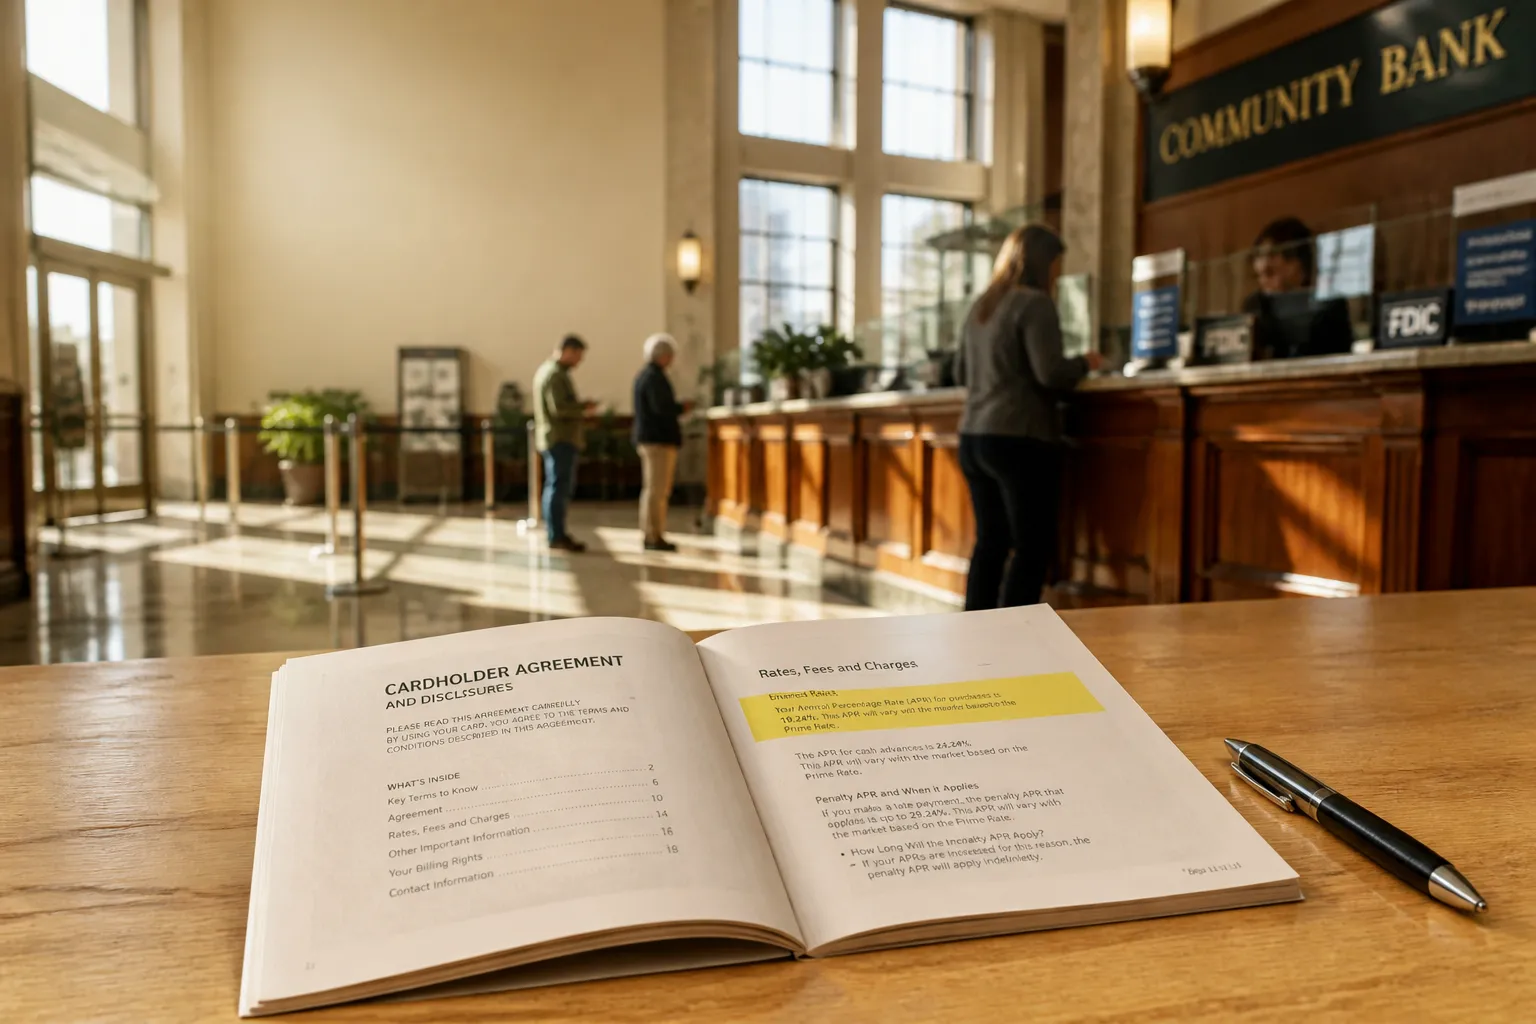
What the sources do not give us is the exact wording issuers use, where the line sits on the page, or how it is calculated on a statement. No sample cardholder agreement was included. Two of the Regulation Z pages cited in the research returned only navigation text, so nothing could be drawn from them. Treat any claim about the line's layout, including mine, as something to check against your own issuer's disclosure and the current regulation text.
One practical habit helps anyway. Read the interest and fee sections together. A minimum charge is a small piece of a bigger system, and it only makes sense next to the APR and the balance it applies to.
How credit card interest is calculated
Interest is a percentage charged on borrowed money when a balance carries from one billing cycle to the next. Many issuers work it out daily. They divide the APR into a daily periodic rate and apply it to the average daily balance. So interest accrues every day, not once a month.
Picture two people with the same balance and no grace period. One pays it down on day five of the cycle. The other waits until day twenty-eight. Both are charged daily, but the first has fewer days of interest on the larger amount. That is why paying sooner generally lowers the interest owed when no grace period applies.
For a credit card, the interest rate and the APR are essentially the same thing, and the APR generally reflects interest only, not fees. That is why the fee schedule needs its own read. Your statement must also show each balance category with its own APR and the amount in that category. Purchases, balance transfers, cash advances and promotional balances can each carry a different rate, so one headline APR may not describe the whole account.
Variable rates, penalty APRs and other terms that affect the charge
Most cards have variable APRs that move with an index such as the prime rate. The agreement spells out how and when the rate can change. Fixed rates are less common on cards and can still change, but the issuer has to give advance notice.
Penalty APRs are a separate bucket. Federal law requires 45 days' notice before one can be applied. Late or missed payments can trigger one, and it typically does not apply during the grace period. Introductory APRs are also separate. They cover specific balances for a stated time, so find the end date in the agreement.
The grace period deserves a careful look. It usually covers only new purchases, and generally only if you were not already carrying a balance. Without it, interest builds daily until the balance is paid. If you pay more than the minimum but less than the full balance, the issuer generally must apply the extra to the balance with the highest rate first.
Questions to ask when reading or comparing agreements
Rates and fees differ by issuer. A CFPB data spotlight found that small banks and credit unions offered lower APRs than the 25 largest issuers across credit score tiers. The estimated difference was $400 to $500 a year for a consumer carrying a $5,000 average balance. The same report found average annual fees at large issuers were about 70% higher. Those are averages, and they will not describe every cardholder.
A short list of questions keeps a comparison honest:
- Is there a grace period, and does it cover every balance type?
- Which APR applies to purchases, cash advances and balance transfers?
- Is the APR variable, and what index does it track?
- What triggers a penalty APR, and how much notice comes first?
- How large is the annual fee?
If the agreement does not make an answer clear, ask the issuer directly and keep the written reply.
Limits of the available information and where to check next
Here is what stays open. The sources do not say how the minimum interest charge is computed, what typical amounts look like, or how to find the line in a specific document. They also do not address whether state law changes any of this.
The CFPB has proposed lowering the safe harbor for credit card late fees to the lesser of $8 or 25% of the minimum payment. That was a proposal in the materials reviewed, and its final status and effective date were not confirmed. Check current CFPB pages before relying on it.
This article is educational only. It is not personal financial, legal or tax advice. For a specific account, start with your issuer's disclosures and the CFPB's consumer resources, including its explainer on how card interest is calculated.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


