










Your debit card is in your wallet. Your number may not be. Card data gets taken in data breaches and through hacked Wi-Fi, and the plastic never has to leave your pocket. This guide covers how to check for signs of trouble, what the federal timing rules say, and where public sources stop short of an answer.
Why a debit card can be exposed without the card leaving your wallet
A lost card and a compromised number are different problems. With a lost card, you know the thing is gone. With a compromised number, nothing looks wrong. The CFPB notes that card data can be stolen through breaches or Wi-Fi hacking even while the card sits where you left it [2].
Timing is the sneaky part. Fraudulent debits or charges may show up months after the data was stolen [2]. A quiet account does not prove nothing happened. It may only mean the thief is waiting. That is why the CFPB advises watching accounts closely when card data is hacked, even if you are not sure your information was exposed [2].
Checking your account activity for unfamiliar merchants
The routine is dull, which is the point. Check transactions often through online or mobile banking if that makes it easier. Open paper statements and read them. The shorter the gap between a bad charge and your report, the better your position [2].
Here is what to look for. These are the red flags the CFPB describes [2]:
- Merchant names you do not recognize. Names tied to places outside your area deserve extra attention.
- Small amounts. Thieves sometimes test a card with a small charge before going bigger. A small unfamiliar debit counts as much as a large one.
- Late arrivals. Activity that appears months after a suspected theft is still a flag.
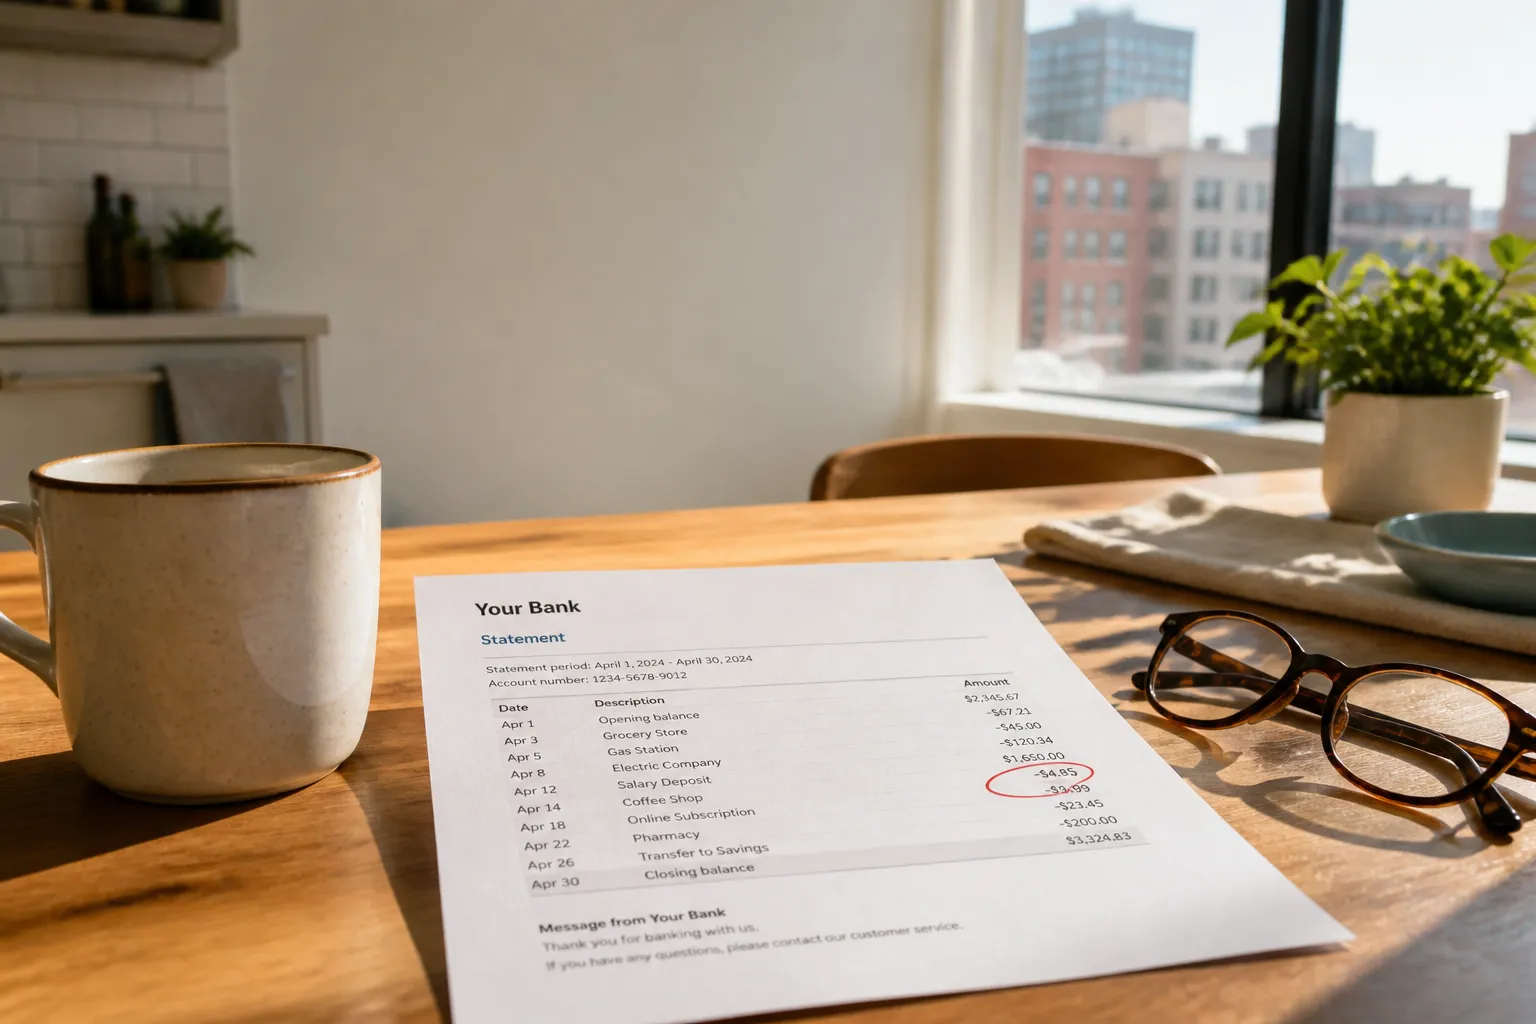
Now the limit. An unknown merchant on your statement is a reason to call your bank. It is not proof that any particular merchant was breached. The public sources reviewed do not explain how to tell which merchant was the source of a breach [2][5][6][7][8].
- Note the date, amount and merchant name of anything odd.
- Check whether it is a pending item or a posted one.
- Contact your bank or card provider instead of guessing.
Using state breach-notice sources and what they can and cannot tell you
California and Washington both publish breach notice resources. California's Attorney General runs a searchable list of data security breaches [7]. Washington's Attorney General offers a data breach resource center and a notifications directory [6][8]. These show breaches reported to state officials.
That is useful background. It is not a card-exposure test. The sources describe notification laws and directories, but they do not say how to search them for a particular merchant, or how a notice applies to a debit card number. A missing listing does not mean your data is safe. Not every incident ends up on a list, and the sources do not say otherwise.
Your bank holds the transaction records. It can see what happened on your account. So ask it directly about anything suspicious.
Federal timing rules for unauthorized debit transactions
Regulation E, found at 12 CFR Part 1005, sets the rules on consumer liability for unauthorized electronic fund transfers [1]. Those transfers include ATM transactions, debit card purchases, some online bill payments, and automatic payments deducted from your account [4].
The clock matters. The CFPB lays out these points [4]:
- Report a lost or stolen debit card within two business days of discovering the loss, and you cannot be held responsible for more than the unauthorized amounts or $50, whichever is less.
- Report after two business days, and you could be responsible for up to $500 in unauthorized transactions.
- Miss the 60-day window for an unauthorized withdrawal shown on a statement, and you could also owe the full amount of transactions made after day 60 and before you notify the bank or credit union.
Two dates count: when you discovered the problem and when you told your institution. Write both down.
After you notify the bank or credit union, it generally has ten business days to investigate. If it finds an error, it must correct it within one business day, then has three business days to report its findings to you [4]. These are general rules. Real outcomes depend on the facts of each case.
What to do when you spot suspicious activity
Call first. Contact your bank or card provider right away. Prompt notice is what the timing rules hinge on [4].
For a debit card theft, the CFPB advises canceling and replacing the card before more transactions come through, and considering a PIN change [2]. Those are general steps. The sources do not describe how to request a new card or what a bank's dispute process requires beyond the timelines above.
Some questions stay open. The sources do not say whether a debit card number alone, without the PIN or the card, can be used for fraud. They do not explain how card networks handle disputes either [2][3][4]. The OCC page on card fraud was cut off in the version reviewed, so its advice is not covered here [3].
Credit cards are only touched on. The CFPB says similar protections may apply, but readers with credit card concerns should check the CFPB and their issuer's disclosures directly [2][4].


