










On the first Sunday of the month, a household may sit down to review rent, groceries, and utility bills, then realize another adult's costs have become part of the regular picture. That can happen when a child never moved out, or when one comes home after a job change, school, or a rise in housing costs. A calendar-based budget makes the new arrangement easier to see. It does not require every family to follow the same rules.
A simple monthly routine has three steps:
- Start with the month: list recurring bills and the dates they are due.
- Mark the shared costs: note which amounts may change with another adult in the home, such as groceries or utilities.
- Schedule a review: choose a date to check the plan again, especially if income or work hours may change.
Three questions can guide the first conversation at that table:
- Which expenses are fixed, and which could rise or fall from month to month?
- What does each person understand the household arrangement to include?
- When will the household revisit the plan if circumstances change?
Living at home is no longer unusual
In 2025, 49% of adults under 30 lived with a parent, a 12 percentage-point increase from 2019, according to Federal Reserve survey data cited by the Center for Retirement Research at Boston College. The report connects the change with education debt and a weak entry-level job market for graduates, along with housing costs that affect people across age groups. That context can help families start a money conversation without treating living at home as a personal failure.
The source is an opinion column by an economics professor and research fellow, not a budgeting guide. It describes a broad trend and does not set a standard way to divide rent, food, or utilities. Treat the figure as background for your own household, not as a formula. Read the Center for Retirement Research discussion.
Put bills and due dates on the calendar
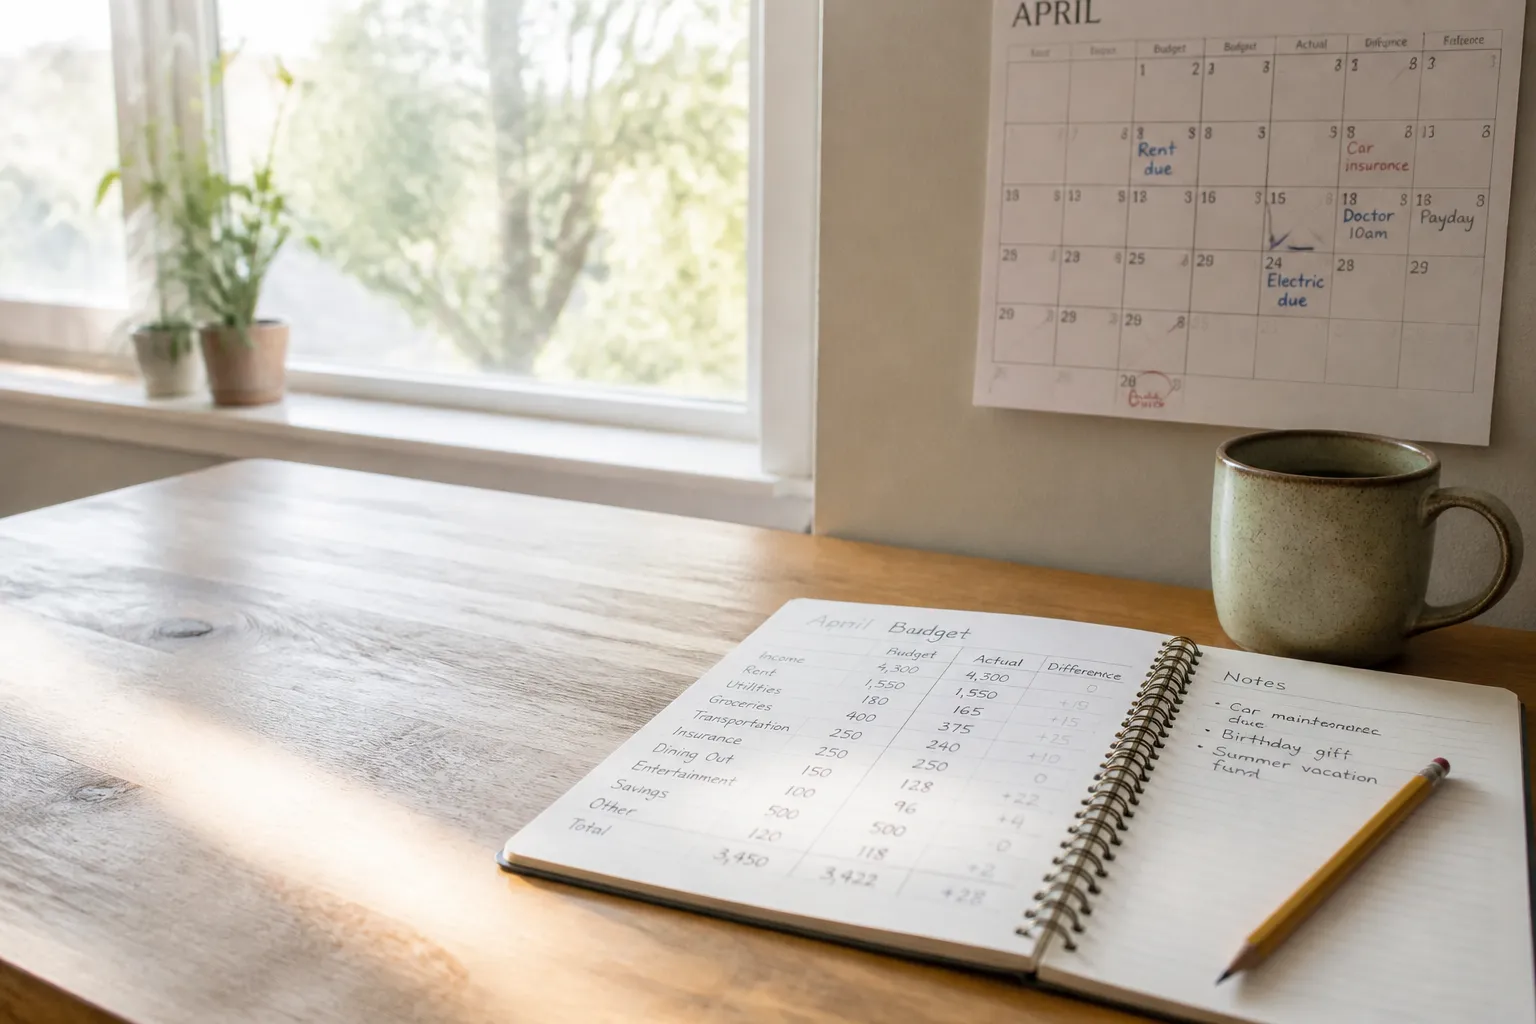
Begin with a blank monthly calendar and write each bill on the day it is due. Rent or mortgage, utilities, phone plans, insurance, car payments, and subscriptions all belong there. Add any loan payment that one person makes on behalf of another. Then mark the days each adult gets paid. Seeing income and bills on the same page shows which weeks are tight, and that can matter more than the monthly total.
The same column says rents have grown faster than inflation since 2007 and that the rental vacancy rate fell by 30 percent in its comparison of housing measures. It also notes that unemployment for adults ages 25 to 34 more than doubled during the Great Recession and was back to normal by 2016. Those figures describe changes over time. They do not predict one person's next job or housing options.
Track the costs that move
Fixed bills are easy to list. Groceries, electricity, water, gas for the car, and household supplies are harder, because they shift with the season and with who is home. A general approach is to save receipts or check bank and card statements for two or three months, then write the actual totals in the notebook next to each category. After a few months, a rough range for each line is more honest than a guess.
It can also help to note what changed. If the grocery total rose after the move, the notebook should say so. If a heating bill jumped in winter, mark the month. These notes turn a vague feeling that costs are up into a number the household can talk about calmly.
Decide how to share costs, and when to look again
The sources reviewed for this article do not say how parents and adult children should divide household costs, so there is no sourced universal split. What follows are general suggestions. Write down which expenses the adult child will cover, which the parent will cover, and which will be shared. Some families tie a contribution to income, some choose a flat amount, and some cover specific bills. Any of these can work if everyone understands it.
A short written note can record what the arrangement includes, how and when a contribution is paid, and what happens if work hours or income change. It does not need to be formal. It gives everyone the same reference point. Then pick a review date and put it on the calendar, perhaps three months out, rather than promising to talk about it later. The Consumer Financial Protection Bureau lists adult financial education resources that families may want to browse.
Keep tax questions separate
Whether a parent can claim an adult child as a dependent is a federal tax question, and a household budget cannot answer it. Qualifying tests, age limits, and credit rules can depend on a person's circumstances, so this article does not try to state them. For current information, check the IRS pages on dependents and Publication 501. A complicated situation may call for a qualified tax professional.
Protect room for the parent's own expenses
Support for an adult child can last a few months or several years. Put the parent's own commitments on the same calendar: retirement contributions, an emergency fund deposit, medical costs, home repairs. List them first, not with whatever is left after the bills. If the numbers do not leave room for those lines, that is worth knowing early.
At each monthly check-in, ask whether the arrangement still fits the household's income, bills, and plans. Ask whether both adults share the same understanding of what happens if a job, expense, or move changes. There may be no single right contribution or timeline. A marked calendar, a short written note, and a review date make the real choices easier to discuss.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


