










On December 14, a household may already be looking ahead to January rent, school costs, groceries, and the next payday. When one adult’s earnings support the family, the calendar matters: a monthly total can look workable while bills arrive before money does. A written budget can help show what is coming in, what is due, and what may need a closer look. The steps here are general education, not personal financial advice.
What a budget does for a one-income household
A budget is a written plan for how a household expects to spend and save income during a month. For a family relying on one earner, it can make the timing and size of obligations easier to see. A higher-than-usual utility bill or a delayed paycheck can change the picture quickly. Putting the amounts on paper gives the household something concrete to review.
A budget does not guarantee that every bill will be covered or that a savings goal will be reached. It can, however, help organize decisions about bills, debt payments, savings, and everyday spending. The Consumer Financial Protection Bureau describes budgeting as a way to pay bills without running out of money during the month, work toward savings goals, and prepare for emergencies. The CFPB’s budgeting overview lays out general steps for making a plan.
Try a simple reflection prompt: if income changed next month, which number would you check first? Knowing the household’s current income and expenses can help answer that question sooner, before a bill is already late.
Step 1: Write down every source of income
Start with the money expected to come into the household. Record the main paycheck, then consider any other sources, such as child support, gig or self-employment income, or government benefits. The point is to see the whole income picture, not to assume that one wage amount tells the full story. The CFPB offers an Income Tracker for recording income sources.
If pay varies, a plan based on the most optimistic month may leave a gap later. Oregon’s financial regulator uses a straightforward example: two estimated paychecks of $1,500 add up to $3,000 for the month. When amounts are uncertain, a conservative estimate can make the plan less dependent on money that may not arrive. Oregon’s budgeting guide explains this approach.
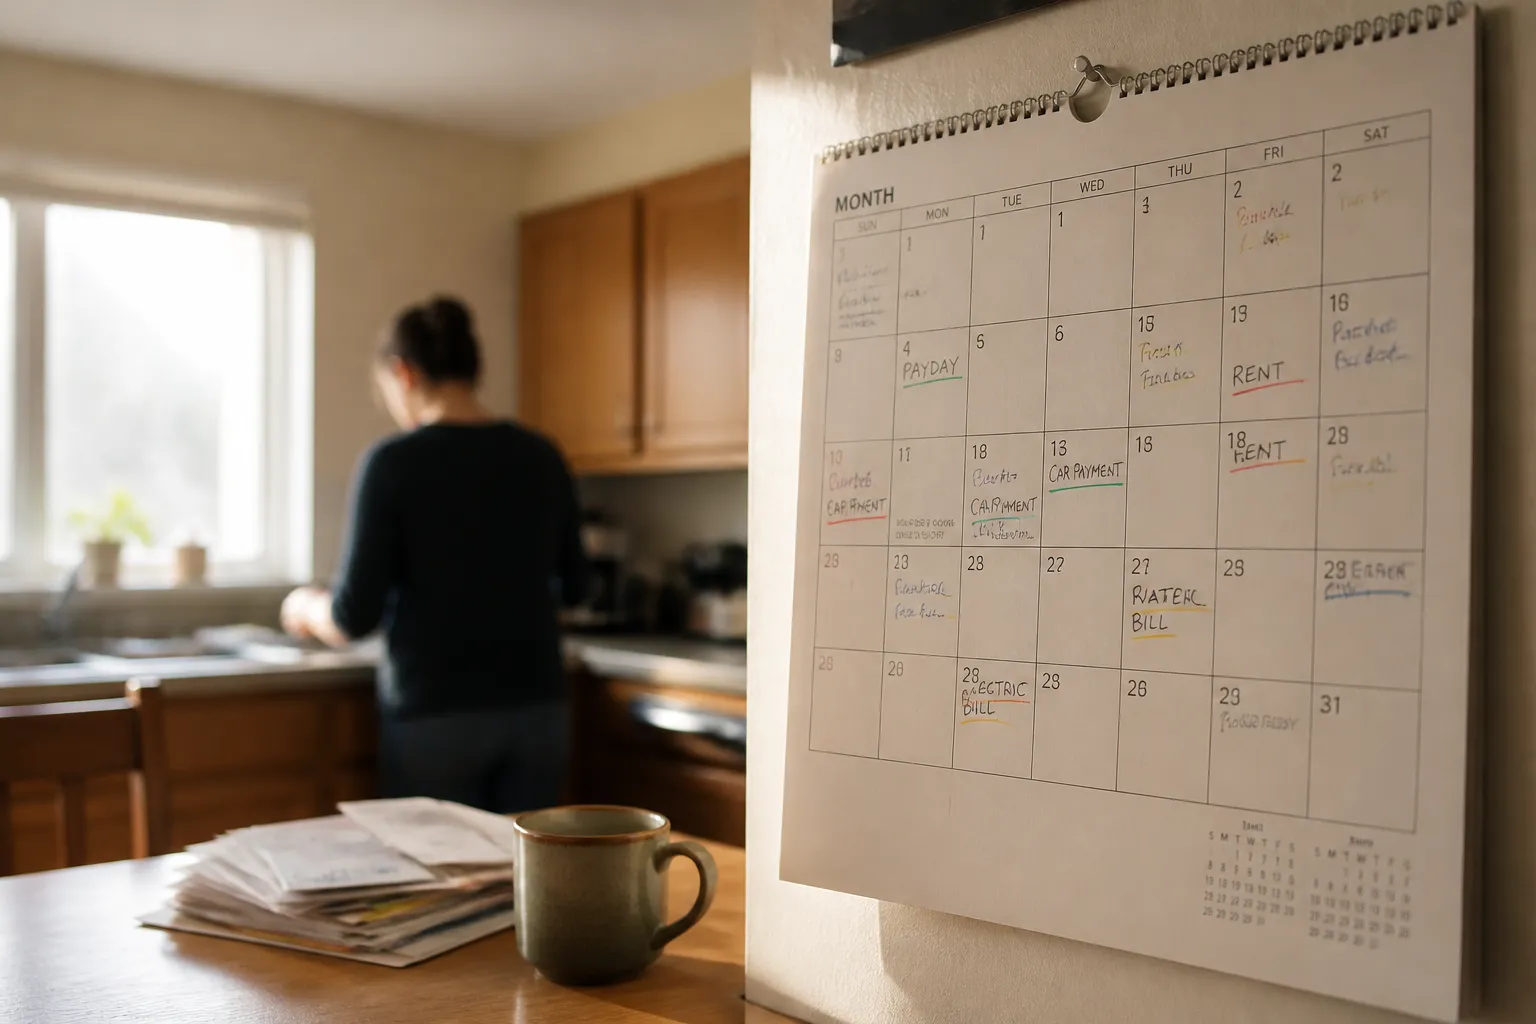
Mark expected pay dates on a calendar as well as noting the monthly total. Ask: which bills are due before the first expected deposit, and which are due near the end of the month? The answer can reveal a timing issue that a single monthly figure hides.
Step 2: Track spending before setting targets
It is hard to make a useful plan from guesses alone. Review several months of checking account and credit card activity, keep receipts, or write purchases in a notebook. Include small, routine expenses as well as larger bills. A few separate purchases can add up over a month, even if each one seems minor at the time.
Next, sort spending into categories that fit the household. Housing, utilities, food, transportation, child-related costs, eating out, and entertainment are possible starting points. The Consumer Financial Protection Bureau calls spending tracking one of the more demanding parts of budgeting. If reviewing everything at once feels like too much, start with one week and then continue. Its spending assessment guidance describes ways to compare records with actual spending.
Make an “as-is” budget first, meaning a record of what is happening now rather than an ideal version of the month. Add a miscellaneous category for costs that do not fit neatly elsewhere. That line can help keep the plan from treating every unclassified expense as a surprise.
Step 3: Put bills and flexible costs on the calendar
Once income and current spending are recorded, estimate fixed expenses first. Rent or a mortgage, insurance premiums, and loan payments are examples of costs that may recur on a set schedule. Then estimate variable expenses such as groceries and fuel. The amounts may move from month to month, so compare the estimates with recent records instead of treating one month as a rule for every month.
Now place due dates and expected pay dates together. Imagine a paycheck arriving near the middle of the month while housing costs are due on the first. The monthly totals might appear to balance, but the calendar shows a cash-flow gap to account for. A written plan can make that mismatch visible. It does not determine what change is right for a household, but it gives the family clearer information to consider.
Leave room for monthly expenses and savings goals rather than assigning every dollar to a category that does not reflect real life. At the same time, too much unassigned room can make it easier for unplanned spending to absorb the apparent surplus. A useful check is to compare the plan with the next month’s actual dates and ask: what cost is missing, or what estimate needs another look?
When money is tight, review the plan early
If income falls or expenses rise, begin by checking whether current income still covers current expenses. Reviewing the budget soon after a change may leave more time to assess options than waiting until bills are past due. A general sequence is to identify what can be spent, track it, look for possible cutbacks, consider ways income might increase, and make a plan for keeping up with bills. The University of Wisconsin’s financial education guide discusses these steps.
A change in income affects the household, so a family conversation can help set expectations. Children may be able to understand that some purchases or activities need to be postponed for a period. The conversation can stay concrete: which calendar item is changing, and when will the family review the plan again? If a bill may be difficult to pay, contacting the creditor early to ask about available options is generally more useful than waiting until after a missed payment.
What these general steps cannot tell you
The sources used for this article provide broad budgeting guidance. They do not give a special formula for families with one earner, typical costs for housing, child care, food, or transportation, or a recommended savings amount. A family’s expenses and income timing can differ widely, even when the household size is similar.
The materials also do not explain how taxes, child-related benefits, or public assistance programs affect a particular household’s budget. Those details depend on circumstances and are outside this general overview. For now, a useful next step is simply to put the next month’s income, bills, and expected variable costs on one page, then compare that plan with what actually happens.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


