










A premium can look small on a bill and still be hard to cover if it lands beside rent, groceries, and several other automatic payments. A household budget works better when it tracks both the amount and the date each payment comes due. Life insurance adds two more questions. How long is the coverage meant to last, and is the premium likely to change?
Start with the purpose of the coverage
Price is only one part of the choice. The Insurance Information Institute, or Triple-I, says the first priority is a policy that meets a household's needs. A low premium does not save money if it pays for benefits the household does not need, or if the coverage falls short. Life Happens also warns that losing an earner's income can leave loved ones in a difficult position. Those points make the budgeting question more specific than "What is the cheapest premium?"
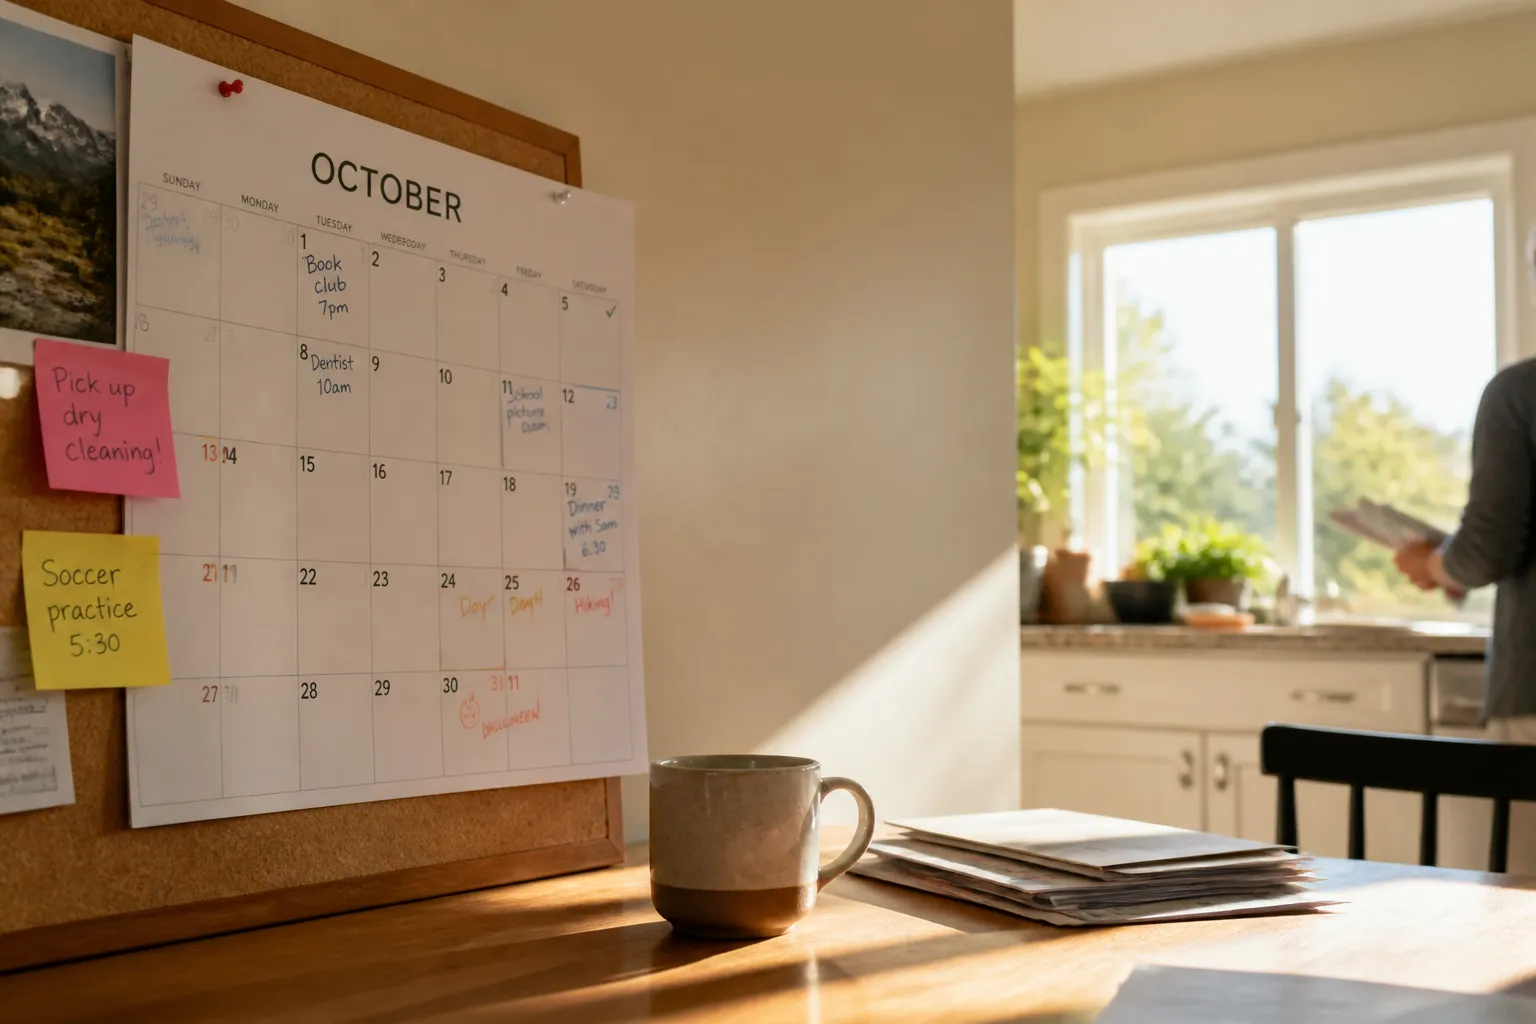
Picture a hypothetical household looking at its calendar in March. A policy payment might be due a few days before payday, while another bill auto-pays at the start of the month. Listing recurring payments by due date can show whether the strain comes from the total cost or from the timing. The Consumer Financial Protection Bureau offers general guidance on reviewing spending and setting a spending amount. Those pages are written for home-buying preparation, not life insurance. Still, the basic task of mapping income and expenses can make recurring bills easier to see.
- Write down the coverage purpose and the period when it matters, such as the years children are at home or the time until a debt is paid off.
- Put the premium's due date on the same calendar as other recurring bills and income dates.
- Check what the quoted premium covers before treating a lower price as a saving.
Match the policy period to the need
Term life insurance covers a set period and is generally the more affordable type, according to Life Happens. Triple-I describes a 20-year term policy as one possible match for the years a parent expects to fund a child's college costs. Term rates per thousand dollars of benefit are lower than permanent rates, so term coverage may fit a larger benefit into a limited premium budget. The tradeoff is that the coverage runs for a defined term, not automatically for life.
Permanent life insurance lasts for life and includes a cash-value component. Its premiums generally stay level, but they are higher than term premiums. Some permanent policies build tax-deferred cash value that can be borrowed against, with the death benefit as collateral. That is a policy feature. It should not be counted as spare money for regular bills. Life Happens also describes a term-and-permanent combination for people who want larger coverage now and lifelong coverage later. The right comparison depends on the purpose and period of the coverage, not only the first payment.
Plan for changes in the premium
A monthly budget can make a premium look steady even when the price may change later. Term premiums are lowest when a person is young, and they generally rise if the policy is renewed after its term ends. Some term policies allow renewal, but others may require a medical exam to get the lowest renewal rates. A convertible term policy may allow conversion to permanent coverage without a medical exam, in exchange for higher premiums. Before building renewal or conversion into a long-range plan, it makes sense to ask what the future cost and conditions would be.
Permanent premiums generally stay level, which can make them easier to forecast. They start higher than term premiums, though. A household comparing options can mark both the current payment and any known future change on its calendar. The sources used here do not give typical premium amounts by age, health, or coverage level, so this article cannot offer a reliable dollar estimate. Actual quotes are the only way to compare actual costs.
Compare more than the monthly amount
For essentially the same policy, annual premiums can differ by hundreds of dollars among financially strong companies, according to Triple-I. Getting several quotes can reveal those gaps without changing the coverage being compared. It can also help to ask which rate class applies. Insurers sort applicants into classes such as preferred non-tobacco, standard non-tobacco, preferred tobacco, and standard tobacco. Some people with health conditions are offered impaired-risk or nonstandard rates.
Payment timing can affect the bill too. Some insurers discount a full year's premium paid in a lump sum, or paid twice a year, compared with quarterly or monthly payments. A discount only helps if the larger payment fits the household's cash flow. Life Happens also notes that some insurers discount at certain coverage levels, so $250,000 of coverage may cost less than $200,000. Asking about nearby amounts can be informative.
- Ask what rate class is being quoted and what information could change it.
- Compare quotes for the same coverage period and benefit, then check the total cost under each payment schedule.
- If comparing policies with cash value, ask how their net cost index figures differ. Triple-I notes that the index combines premiums and cash value, and that small differences may not matter because the figures are approximations.
- Check whether the company has high ratings from two or more independent rating agencies, as Triple-I recommends. The cited material does not explain how to verify those ratings.
Check employer coverage and calendar risks
Employer group life coverage is often subsidized, but it is not necessarily cheaper than an individual policy for every person. Comparing the group cost with individual quotes at the same age and health can clarify the difference. Group coverage can also end when a job ends, so relying on it alone may leave a gap. A household reviewing benefits can note when enrollment happens, what occurs if work ends, and whether any separate coverage would continue.
Triple-I also points to a tax detail. For group coverage above $50,000, IRS tables set the cost of the amount over that threshold, and that cost counts as taxable income. The effect on take-home pay depends on the person's situation. A tax professional can say more than a payroll deduction line can.
On a household calendar, small premiums become easier to judge when they sit beside paydays, renewal dates, and work-benefit deadlines. One simple habit is to mark the premium due date in a different color than payday. If the two dates sit far apart, timing may be the real problem, and a different payment schedule may be worth asking about. If they sit close together, the monthly amount or a later increase may deserve more attention.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


