Credit repair companies may charge for work that begins with reading a credit report, spotting entries to question, and sending disputes. Consumers can take those steps themselves. The harder part is knowing what is actually wrong, keeping useful records, and spotting a company that sells certainty before it has looked at the facts.
A promise to erase debt for “pennies on the dollar” deserves a pause, especially if no one has reviewed your situation.
Start with the work a company might charge you to do
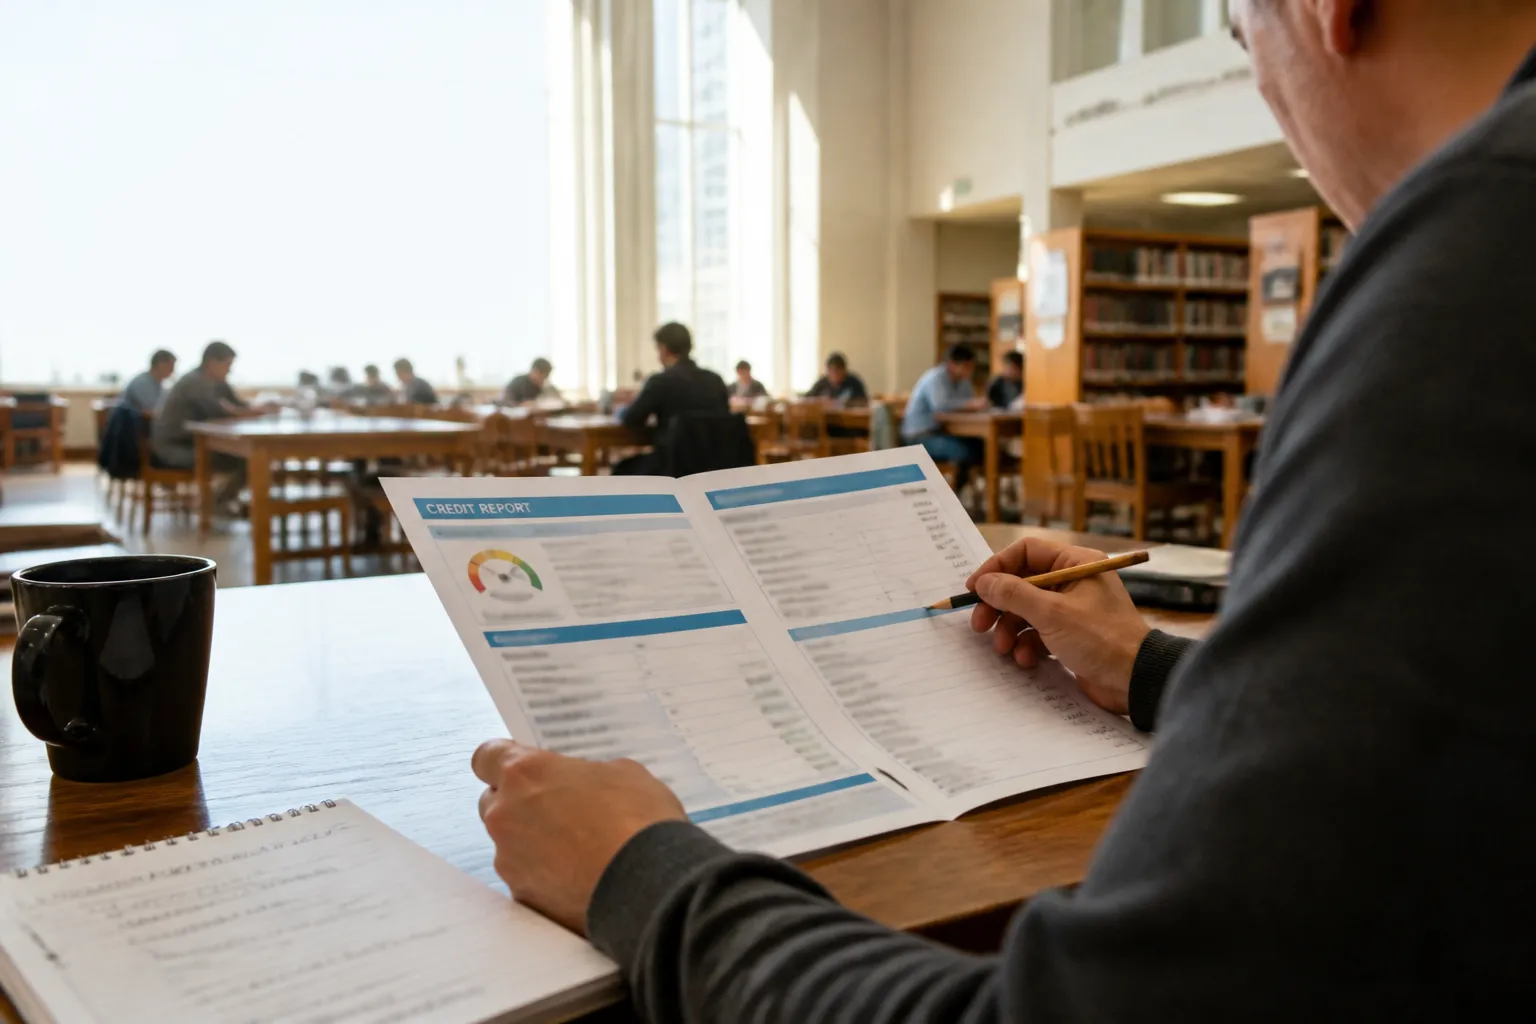
Checking your own credit reports is a practical first step. Look for accounts you do not recognize, entries that appear twice, or details that seem wrong. A company has no exclusive access to this review. The sources provided for this piece do not cover how to request a free report, so look for the official channel through a government agency such as the FTC or the Consumer Financial Protection Bureau. Be careful with look-alike sites.
Keep the question specific. “This account is not mine” gives the reader a clearer issue to review than “my credit is bad.” Note the name of the bureau or business, the item in question, the date you contacted it, and the reply. Save copies of every letter. Those habits do not guarantee a correction or a score change. They do make it easier to follow what happened.
The FTC’s Fixing Your Credit FAQs page is the agency’s consumer guidance on this topic. The text available for this article did not include its answers, so read the page itself and treat its current instructions as your process guide, not a company’s broad promise.
Separate a dispute from a promise to erase debt
Questioning an item you believe is inaccurate is different from paying someone to make a debt disappear. A dispute asks for information to be reviewed. It does not settle in advance that the information is wrong, and it does not promise that a report or score will change. Be wary of any pitch that treats a desired result as certain before the company has examined your situation.
The FTC warns that dishonest debt-relief companies may promise to remove debt for “pennies on the dollar” without first looking into a person’s financial or tax circumstances. The agency also cautions that a company’s approach could leave someone further in debt with local, state, or federal tax authorities. A short slogan cannot account for those consequences.
Credit report questions, debt settlement, and tax questions are different problems. If an offer bundles them or says one service will solve everything, ask what work will be done and what facts support the claim. This article is general education, not an assessment of any particular debt or tax situation.
Check the fee and the pressure before you sign up
One concrete warning sign in FTC guidance is a service fee charged before any work has been performed. If a company asks for money up front, ask what specific work is already done and what the charge covers. The FTC’s Spot the scams when fixing your credit alert addresses companies that make promises before reviewing a consumer’s circumstances.
Pressure can make a weak offer sound urgent. Scammers may call, text, or email while pretending to represent a familiar organization. The FTC also notes threats of arrest used to frighten people into paying. A caller’s claimed identity is not proof. Pause, verify who contacted you through a channel you trust, and do not let a threat rush a payment.
Two plain questions can expose a lot: “Have you reviewed my specific situation before promising this result?” and “Are you charging me before doing any work?” Listen for a direct answer. Vague replies, a guaranteed outcome, or pressure to act now are reasons to slow down.
A simple do-it-yourself review
A self-directed review can be organized into a few manageable steps. It does not require predicting what a bureau will decide or trying to remove every negative entry.
Read the report and mark only entries that look unfamiliar or inaccurate.
Write down the exact detail you want checked and gather records that relate to it.
Use current instructions from the credit bureau or the business that supplied the information, then keep a copy of what you sent and any reply.
That sequence is about staying organized, not gaming a score. A paid company may offer help with paperwork or follow-up, but paying does not turn an accurate entry into an error.
What to confirm before paying anyone
The material behind this overview does not lay out the detailed rules that govern credit repair companies, typical service prices, or cancellation and refund terms. It also does not explain the Fair Credit Reporting Act, which is the federal law most people will want to read about when disputing an entry. Those details matter if you are comparing a service agreement or handling a complicated dispute.
Before agreeing to paid help, read the contract line by line and check current guidance from the FTC or CFPB. If a debt has legal or tax consequences, a qualified professional can review the specific facts. Checking your own reports and asking about entries you believe are wrong are tasks you can begin today. A guaranteed cleanup is a claim to test first.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.