










The school calendar has its own rhythm: a winter break here, a teacher workday there, then a spring week that lands in the middle of a regular workweek. For a household with a child at home and adults still on the job, those dates can bring both a care problem and a bill that arrives before the break begins. Mapping the year can help make those costs visible before registration opens.
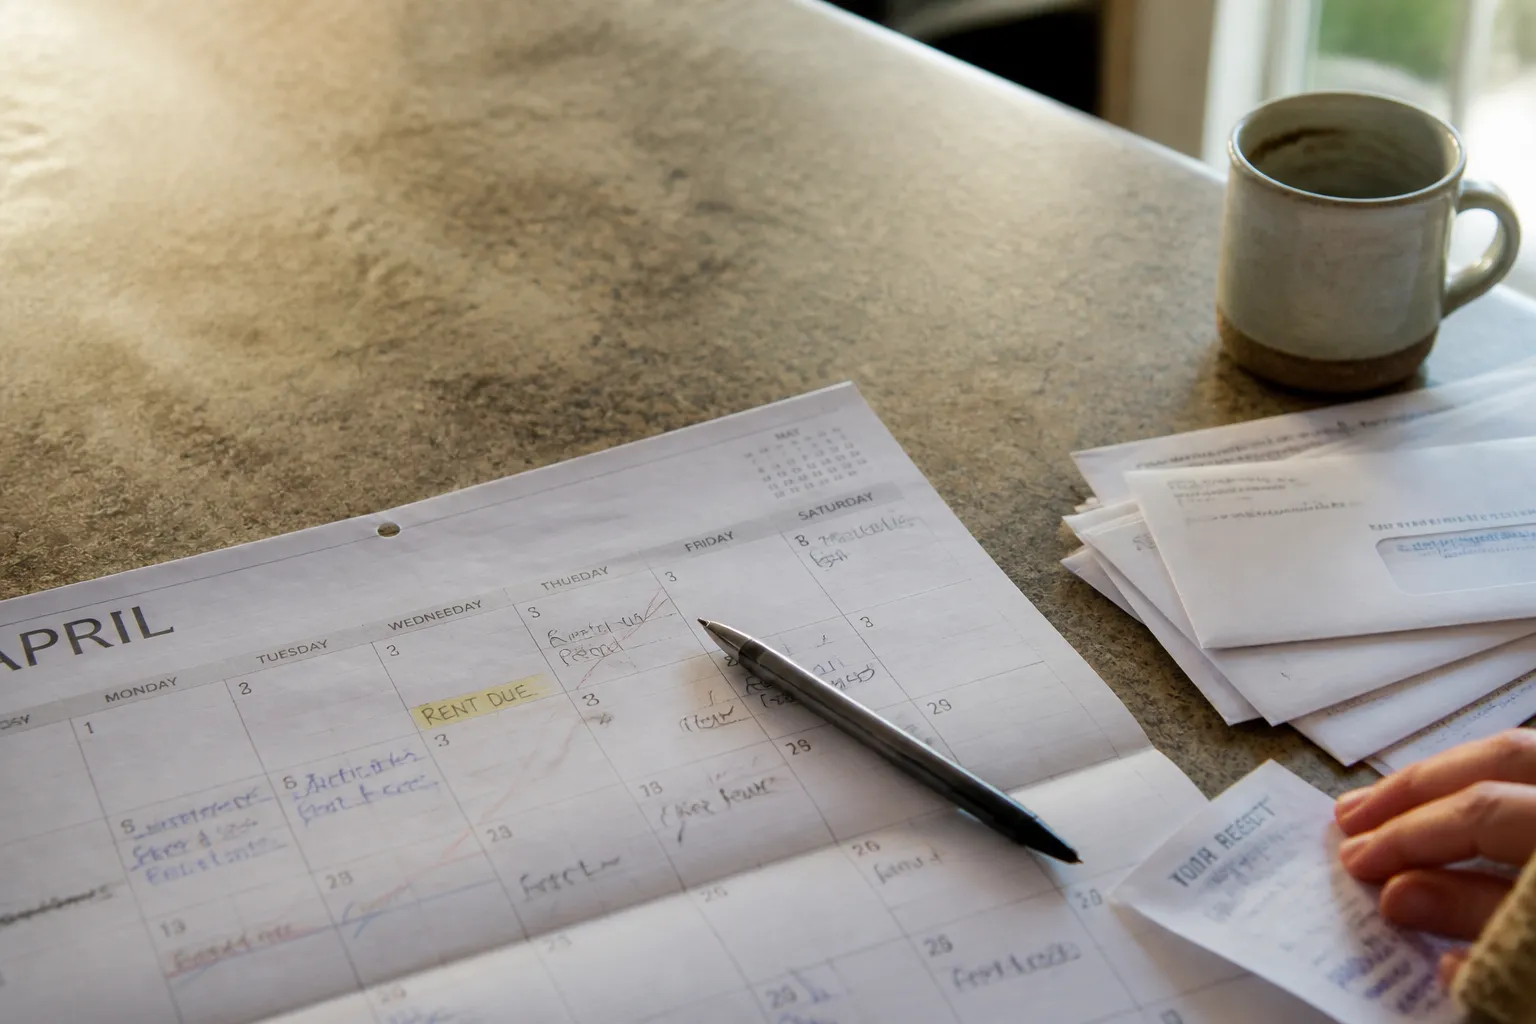
Picture a parent reviewing the family calendar in early fall. The first closure is months away, but the day program wants registration soon, and payment is due well before the child attends. Putting the care dates and payment dates on the same calendar shows two separate questions: how will the family cover the bill when it comes due, and could the expense fit federal rules for work-related care?
Those questions are related, but the tax rules do not replace a cash-flow plan. A cost may qualify under federal rules and still be due at a time that is awkward for the household budget. The details below explain what to check, using the IRS rules and the 2026 dependent-care limit as a starting point.
Put the closures and payment dates on one calendar
School closures rarely arrive as one neat block. Thanksgiving week may require a day program, winter break may have different hours, and a teacher workday can leave a single uncovered weekday. Add each date to a yearly calendar, then note when registration opens, when a deposit is due, and when any remaining balance must be paid. That timeline can reveal a cluster of expenses that a monthly budget might otherwise miss.
For example, a family might find that registration for a spring-break program is due while winter expenses are already taking up room in the budget. Seeing both dates together gives the household a chance to consider timing and the amount it can set aside. This is a planning exercise, not a prediction that a particular program or payment option will be available.
Keep the estimated cost separate from the question of tax eligibility. A simple calendar or list can track the program, the dates of care, the child’s age during those dates, the amount due, and the payment deadline. What is the earliest date money needs to leave the account? That answer matters even before the family checks whether the expense qualifies for an employer plan.
Check what the IRS treats as work-related care
The central test is the purpose of the care: it must allow a parent, and a spouse if filing jointly, to work or look for work. The IRS explains the rules in Publication 503. Day camps can count even when they focus on one activity, such as computers or soccer. School-break day camps are generally treated like summer day camps under these rules.
The type of program matters. Overnight camp does not count as work-related care. Summer school and tutoring do not count because they are treated as education rather than care. A program’s name alone may not answer the question, so check what it provides and the dates and hours of care before estimating an eligible amount. Before- and after-care for a child in kindergarten or higher can also count.
The child generally must be under 13 when the care happens. If a child turns 13 during the tax year, expenses can qualify only for care provided up to the day before the birthday. A full-year estimate may therefore be too high for a child close to that age limit. Care at a dependent care center also has a provider rule: the center must meet applicable state and local requirements.
Separate the care charge from extra fees
A program invoice may combine several kinds of charges. Registration fees and deposits count only when they must be paid to obtain the care. A deposit that is forfeited when the care never takes place does not qualify. Before paying, ask what the fee covers and what happens if the family cancels or the program does not go ahead. Keep the written terms with the receipt.
Transportation is another detail worth separating. Transportation counts only when the care provider supplies it, such as a camp bus. A parent’s gas or a separate carpool arrangement does not count under the rules summarized here. If transportation appears as a separate line on an invoice, note who provides it rather than assuming that every program-related charge is eligible.
These distinctions can make the estimate more accurate. On a household worksheet, list the care charge, any required fee, and transportation separately. Then mark which facts still need confirmation from the provider. This creates a clearer record than treating the entire invoice as one qualifying expense.
Understand the 2026 limit before open enrollment closes
For tax years beginning after December 31, 2025, Public Law 119-21 raised the federal dependent-care exclusion limit to $7,500 per household. For married taxpayers filing separately, the limit is $3,750. These are federal ceilings, not a promise that an employer plan will let every participant elect that amount. The employer’s plan sets the actual maximum available through that plan.
Open enrollment is the period when an employee chooses how much to set aside for the coming year. Before making that election, check the 2026 plan materials for the plan’s cap and its instructions. Compare the possible qualifying expenses with the calendar, paying attention to the child’s age and which programs meet the care rules. The amount of a household’s actual election depends on its plan and circumstances.
Plan details matter beyond the maximum. The sources cited here do not explain claim paperwork or all plan deadlines, so those details should be checked in the plan documents or with the plan administrator. Do not assume that a federal limit answers questions about how a particular employer plan operates.
Keep the FSA and tax credit expenses distinct
The Child and Dependent Care Credit uses the same underlying expenses as the dependent-care exclusion. The same dollars cannot be counted for both. If a family uses an employer account, it should keep a record showing which expenses were applied there, rather than counting those same expenses again toward the credit.
The credit’s percentages and income thresholds are not covered in the sources used for this article. For those details, consult IRS Publication 503. A running list of receipts, dates of care, provider details, and account payments can make it easier to review the expenses without duplicating them.
A short checklist before committing funds
Before choosing a program or making an election, return to the calendar and ask a few practical questions. What is the employer plan’s maximum for 2026? Does a child’s birthday limit the number of eligible care days? Is the program daytime care, rather than overnight camp, school, or tutoring? If it is a dependent-care center, does it meet state and local requirements?
Then check the fees and timing. Is a deposit required to secure care, and what happens if the care does not take place? Who provides transportation? When is each payment due? Those answers help distinguish expenses that may qualify from costs that do not, while also showing when the household needs the money available.
A calendar cannot remove every uncertainty, but it can make a scattered set of closure days easier to see. One marked teacher workday, one registration deadline, and one documented fee can be more useful than a vague annual estimate. Revisit the list when the school calendar or program details change, and confirm plan-specific and tax questions with the relevant documents or qualified assistance.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


