










A checking balance can look comfortable on payday and feel tight a few days later. Imagine a household paid every other Friday, with rent due Monday and a utility payment scheduled for Wednesday. The calendar gap matters: a checking buffer is money left above the bills and purchases expected before more income arrives. It can reduce the chance that a timing mismatch turns into an overdraft, though it cannot prevent every shortfall.
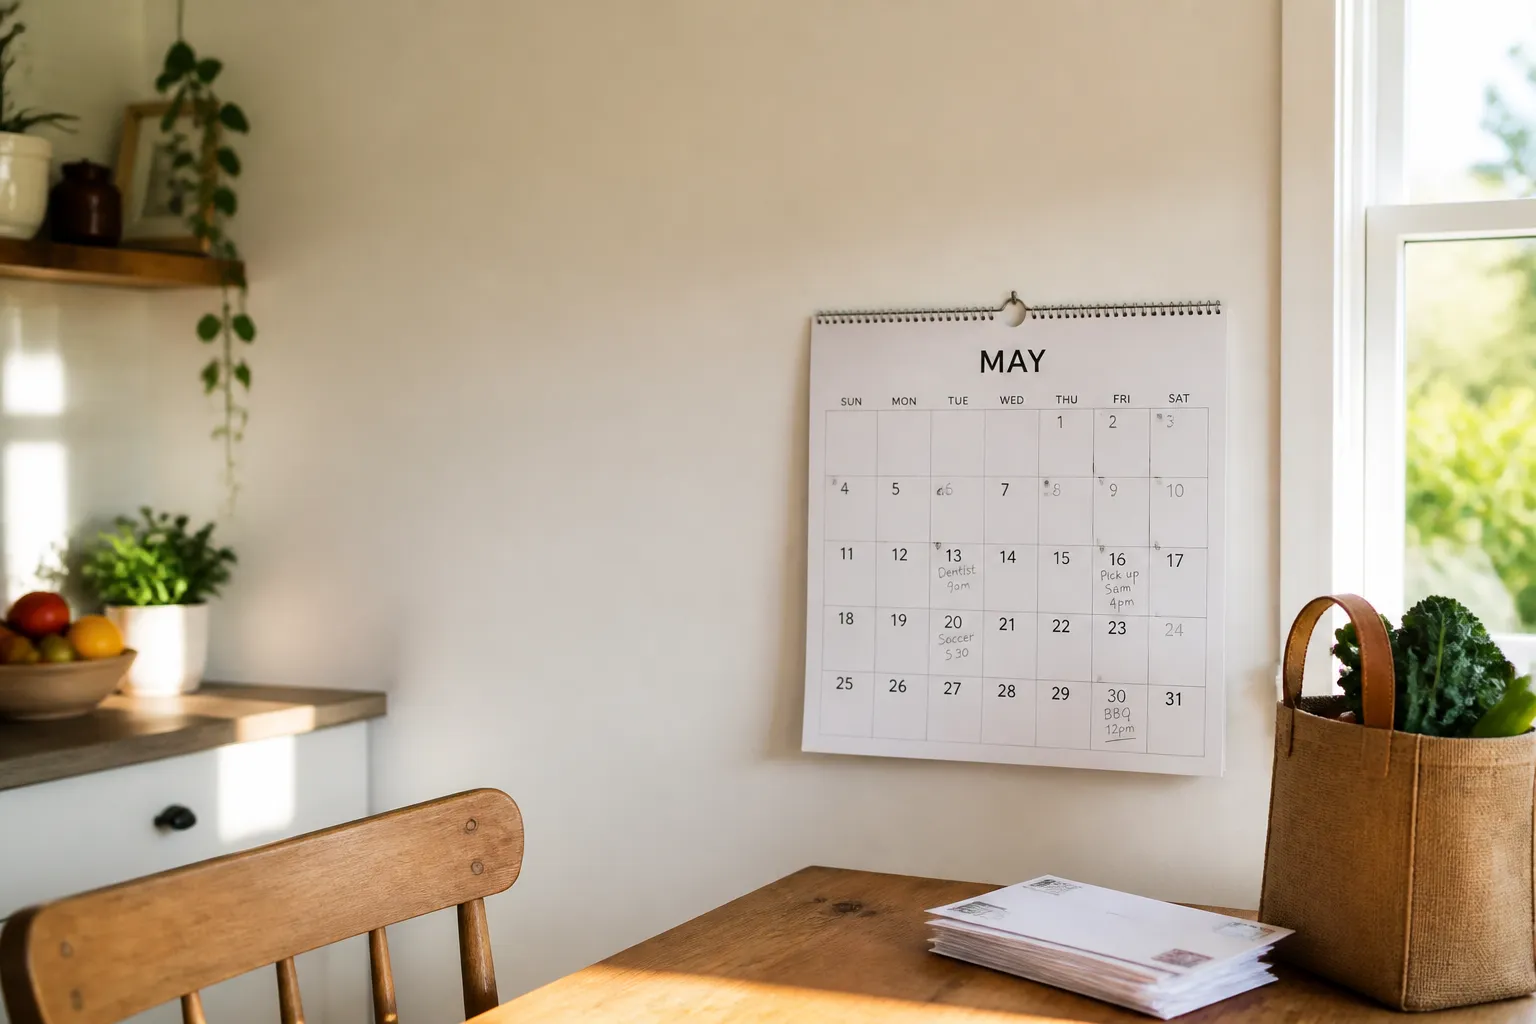
- Mark the dates income arrives and the dates scheduled bills are due.
- Add the regular purchases that usually happen in between, such as groceries or a transit fare.
- Compare that calendar with the checking balance, allowing for payments that may not have posted yet.
- Ask what would happen if a transaction reached the account before the next deposit.
- Check your account’s overdraft settings and the fees or transfer costs that could apply.
- Use those details to consider what cushion fits the household’s bill schedule and spending patterns. There is no universal amount that works for everyone.
What an overdraft actually means
An overdraft happens when there is not enough money in an account to cover a transaction, but the bank or credit union pays it anyway. The account holder then owes the amount that took the balance below zero, along with any applicable overdraft fee. In other words, the missing money does not disappear. The transaction can create a debt to the institution.
Overdraft rules can differ by transaction type. Checks and online bill payments may be handled differently from ATM withdrawals and one-time debit card purchases. Federal rules generally prohibit institutions from charging overdraft fees on ATM and one-time debit card transactions unless the customer has opted in to that coverage. Without it, those transactions are generally declined when funds are insufficient. The Consumer Financial Protection Bureau’s overview of overdraft options explains the distinctions.
Why a small cushion can matter
A buffer is a margin above the money expected to cover upcoming bills and everyday spending. It can help when a deposit and a payment land several days apart, or when a bill is slightly higher than expected. Picture a grocery purchase posting on Tuesday while an automatic bill payment is already queued for Wednesday. A little more money in checking can make that sequence less likely to push the balance below zero.
The fee can be much larger than the purchase that triggered it. The CFPB has described an example in which a $4 coffee led to a $35 overdraft fee, and a small pack of gum later led to another $35 fee. Some institutions charge per transaction, so more than one fee may occur in a day. Others set daily limits. These examples come from older consumer guidance, not a quote for any particular account. Current amounts and terms vary.
A buffer does not have to be treated as money available for ordinary spending. A household reviewing its calendar might notice that the lowest balance tends to occur just before a regular deposit. That low point can be a useful prompt: Which bills arrive then? Are any purchases flexible? Is the balance shown current, or could transactions still be pending? The answers help explain where timing pressure comes from, without implying one target amount suits every household.
Compare the ways an institution may handle a shortfall
One option is to decline debit and ATM overdraft coverage. If a covered transaction exceeds the balance, it will generally be declined rather than paid with an overdraft fee. That can prevent the fee, but a declined payment or purchase may be inconvenient. The trade-off depends on circumstances, so it is worth understanding the account setting before a shortfall occurs.
Another option may be linking checking to savings. If checking is overdrawn, money can move from the linked savings account to cover the difference. A transfer fee may apply, though it is often lower than an overdraft fee. Some institutions may also offer a credit line or linked credit card as an overdraft alternative. That can involve a fee and interest on borrowed money. Compare the actual costs and conditions rather than assuming one approach is free.
Some institutions may charge an extended overdraft fee if a negative balance remains unpaid for a number of days. Fee policies and account terms can change. The FDIC’s consumer information on overdraft and account fees is another place to review general background, but your institution’s current disclosures control the details of your account.
Questions to ask before a tight week
A calendar review can show when a low balance is most likely. Account terms can show what that low balance might cost. Check your current settings in your account information or disclosures, then contact your bank or credit union if anything is unclear. The CFPB issued an advisory about knowing your debit and ATM opt-in status in 2012, so confirm your present status directly rather than relying on an old choice or a past explanation.
- Have I opted in to overdraft coverage for ATM and one-time debit card transactions?
- Is there an extended overdraft fee, and how long can the balance remain negative before it applies?
- What transfer fee applies if checking draws from linked savings?
- If a credit line is available, what fees and interest would apply?
- Does the account have a daily maximum on overdraft fees?
These questions make the trade-offs more concrete. For example, a household deciding between a possible declined purchase and a possible fee needs to know the account’s actual rules, not just the label “overdraft protection.” A linked transfer may have its own limits. A credit option may cost more if a balance is not repaid promptly. Ask for current figures and how each option works with the transactions you use.
Set a buffer by watching the calendar, not guessing
There is no single buffer formula in the sources cited here. A workable amount depends on bill dates, income timing, routine purchases, and the balance a household wants to keep untouched. A calendar can make those details visible: note when recurring bills post, when income is expected, and when the account tends to run lowest. If an amount is being considered, compare it with those real patterns rather than treating a general rule of thumb as a guarantee.
It can also help to distinguish money reserved for near-term obligations from money that appears available in the account balance. Pending transactions and payment timing can make the displayed amount differ from what remains after scheduled expenses. That is why checking the calendar alongside the balance matters. If a larger budgeting problem is involved, a nonprofit credit counselor may offer a free consultation. This article is for education only, not personal financial, legal, or tax advice.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


