










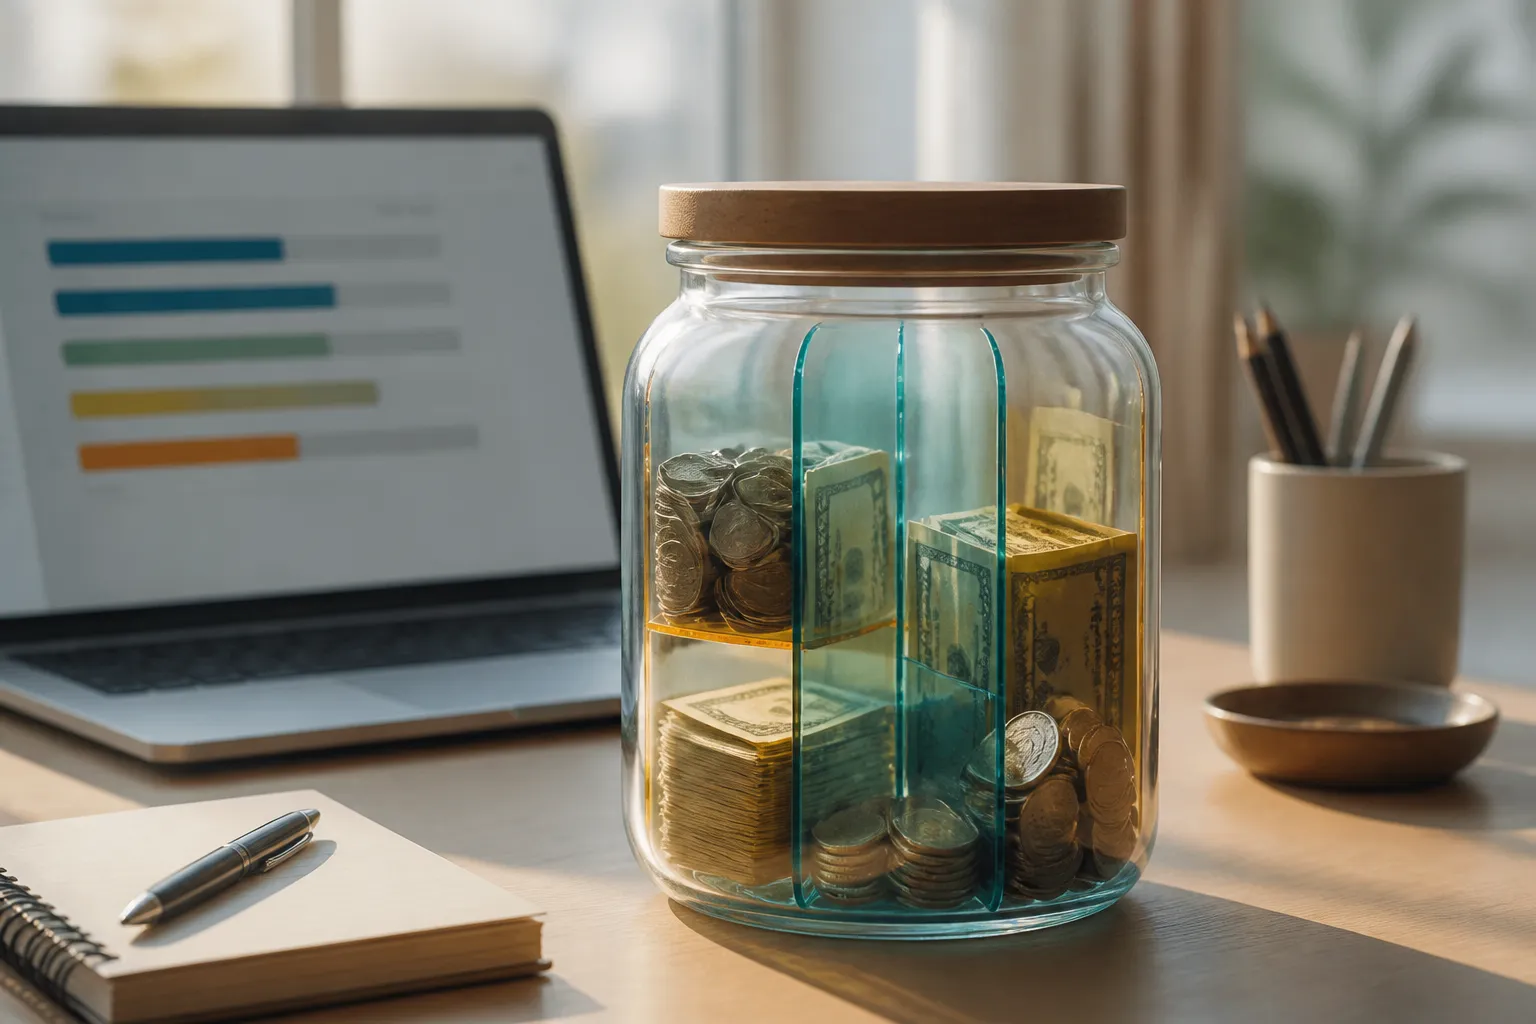
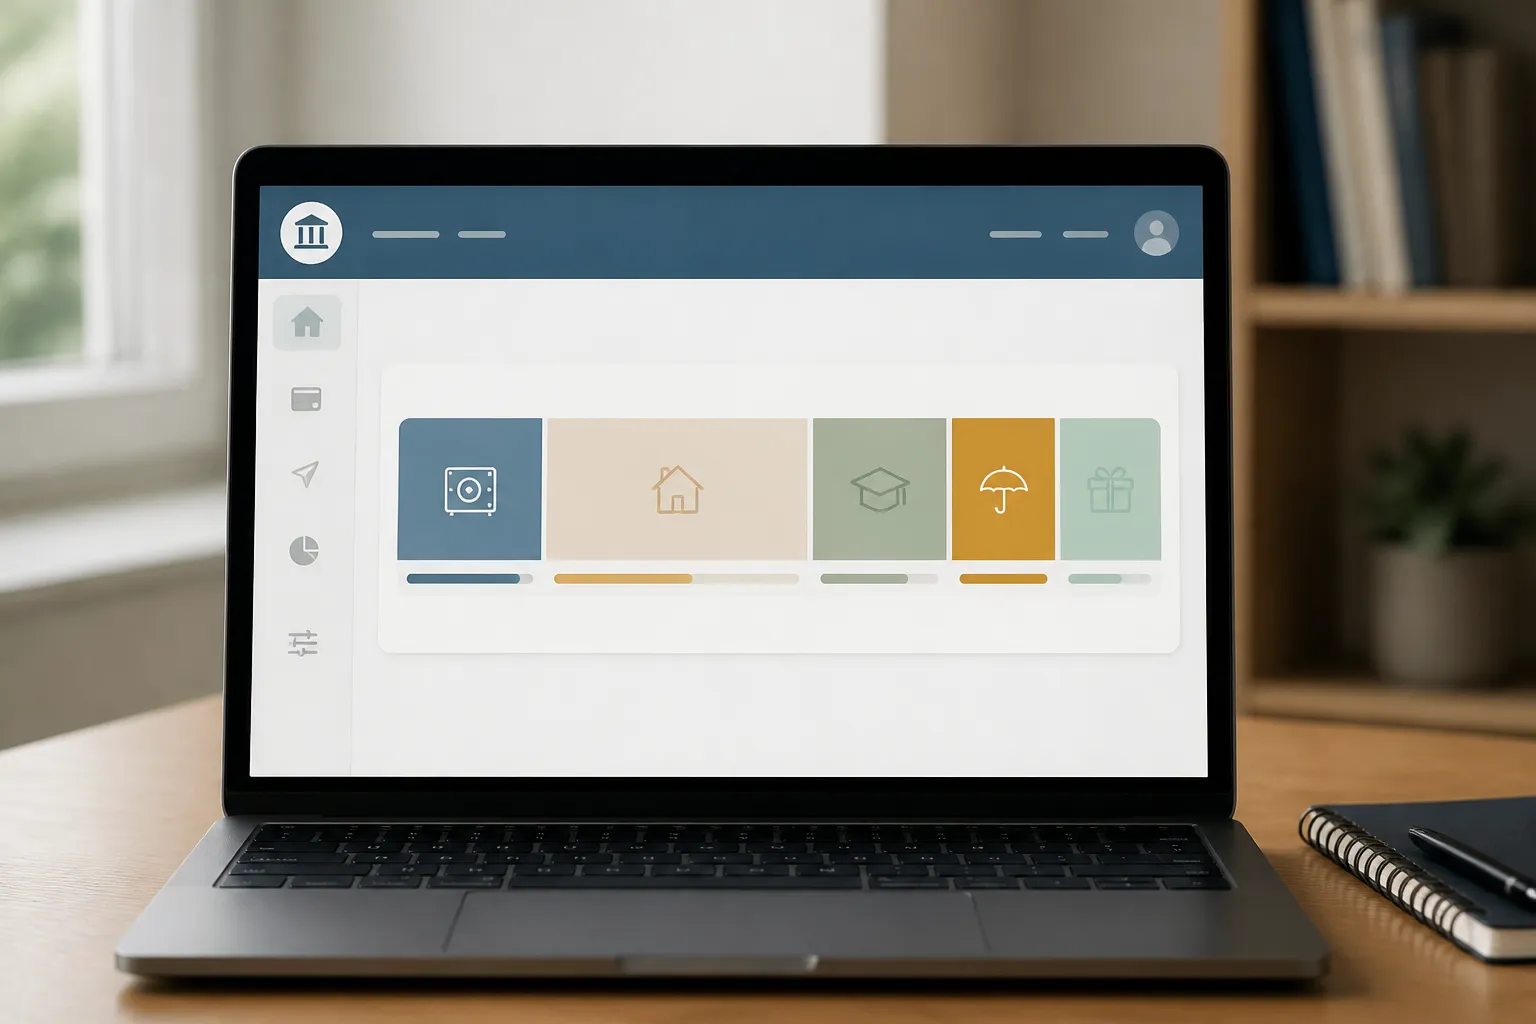
A savings bucket is a digital organizational tool that divides a single savings account into distinct, labeled sub-funds. Instead of opening several individual accounts to track separate goals, a saver creates visual envelopes inside one account for purposes like a car repair, a vacation, or an emergency reserve.
Organizing money under labeled targets changes how you view a balance, but it does not alter the underlying legal structure of the account.
What savings buckets are and how banks frame them
Banks present the savings bucket feature as an antidote to multi-account clutter. The stated premise is straightforward. When people want to save for distinct milestones, they often open multiple deposit accounts across different institutions or within the same branch network. Over time, that habit can create friction. In promotional materials, financial institutions describe buckets through three primary benefits: keeping all funds in one central place, simplifying record-keeping for tax season and budgeting, and mentally separating dollars by purpose.
A common application highlighted by institutions is the isolation of an emergency fund. When emergency reserves sit in a general pool alongside money planned for everyday spending or discretionary leisure, the boundary between necessary cushions and casual purchases can blur. Giving an emergency fund its own labeled digital partition is intended to reduce the urge to spend that cash on non-emergencies. However, these descriptions come directly from bank marketing materials, such as guides on managing savings accounts and bucket structures. They should be evaluated as the institution's own summary of its product features rather than neutral evidence of how well the tool curbs personal spending habits.
How buckets work in routine account mechanics
The operational framework of a bucket system relies on sub-allocations within your main account ledger. Each bucket is assigned a specific financial goal. From there, users can fund these partitions through automatic recurring transfers or through occasional lump-sum deposits. A regular monthly transfer might feed an annual property tax allocation, while an unexpected tax refund or work bonus can be directed entirely into a down payment bucket. This dual setup allows the visual structure to mirror the way cash actually enters the household.
Keeping earmarked funds in designated sub-categories is also marketed as a buffer against accidental spending. Because the account owner sees individual balances for specific priorities, they are less likely to treat the total balance as unallocated surplus. Some marketing materials suggest this arrangement helps protect against overdrafts by keeping secondary reserve funds in the same primary account. Yet an overdraft outcome always depends on the specific bank overdraft schedule, the timing of incoming debits, and individual transaction patterns. A bucket label alone does not change the core overdraft terms of an account agreement.
Viewing money by category while retaining visibility of the cumulative total provides a dual vantage point. It allows account holders to evaluate the health of each micro-goal while verifying how those targets aggregate into their broader liquid reserves. At the same time, banking literature often argues that consolidating money into one bucket-enabled account prevents forgotten accounts, dormant account fees, and neglected interest earnings. While dormant accounts are a recognized risk when juggling multiple banks, institutional materials do not document how much interest consumers actually lose to forgotten balances.
Deposit insurance questions to ask first
Understanding federal deposit insurance is critical when evaluating any savings mechanism. One institutional guide notes that its deposits are insured up to $250,000, including principal and accumulated interest, per depositor, for each qualifying ownership category. This coverage threshold reflects standard federal statutory limits. However, consumers should never assume that dividing money into five, ten, or thirty separate buckets multiplies their insurance protection.
Federal deposit insurance limits apply to the beneficial owner across qualifying ownership categories, not to software-based sub-folders within an application. The official rules outlined in the FDIC guide on general principles of insurance coverage and the agency's index of deposit insurance FAQs explain how coverage is established by legal ownership rights. If a single individual holds one savings account containing $300,000 divided across twenty internal buckets, the balance exceeds the baseline single ownership limit regardless of how those sub-funds are named. Before depositing amounts that approach the statutory boundary, savers should confirm in writing how the bank documents ownership categories and verify which deposit instruments are covered using the FDIC directory of insured financial products.
It is equally essential to separate insurance protections from account activity rules. Deposit insurance shields depositors against the financial insolvency of an insured depository institution. It provides zero coverage for unauthorized transactions caused by shared credentials, transactions the owner authorizes by mistake, or routine account fees. A bucket label is an internal accounting visual, not a shield against balance drawdowns.
Choosing a setup and questions to bring to the bank
Before choosing a bucket-based product or a traditional multi-account setup, evaluate your personal transaction patterns against institutional constraints. The Consumer Financial Protection Bureau outlines this balanced evaluation process in its educational activity on storing my savings, which urges consumers to weigh the specific benefits, access limitations, and potential fees of any savings venue before depositing funds.
- Define distinct targets: Identify which goals genuinely require visual isolation. Starting with two or three foundational buckets, such as a major auto repair reserve and an annual insurance premium, keeps administrative tracking manageable.
- Identify funding patterns: Determine whether each target needs regular weekly allocations or intermittent lump-sum additions from side income or seasonal payments.
- Check feature limits: Confirm the maximum number of sub-funds permitted. For instance, certain institutions allow up to 30 buckets within a single account, while others offer fewer or none at all.
- Clarify movement rules: Ask whether transfers between buckets count toward internal transfer caps or require specific processing windows during the business day.
Do not rely on software marketing pages to determine account parameters. Bring precise questions to the bank customer service team. Ask directly whether the account charges recurring monthly maintenance fees, whether maintaining multiple buckets requires higher overall minimum balances, and how interest earnings are credited across the underlying balance.
Information gaps and red flags to watch for
Consumers who research savings tools online frequently encounter third-party comparison guides and roundups, such as commercial reviews of banks offering savings buckets. Many commercial aggregation websites utilize paid affiliate placements. These portals often disclose that corporate compensation influences the order, placement, and prominence of featured institutions. A high editorial ranking on an affiliate comparison chart does not mean the underlying account terms align with your specific cash-flow needs.
Major information gaps persist across public explanations of bucket features. Educational resources published by institutions, including materials on how to use savings buckets and broader credit bureau guides on savings vaults, rarely outline whether annual percentage yields are calculated identically across every bucket or blended at the account level. They also frequently omit clear instructions on fee schedules, minimum daily balance hurdles, and the exact protocols required to close an individual sub-fund without closing the primary account.
Furthermore, standard product descriptions rarely compare the earning power of a bucket-enabled checking or savings account against alternatives like standalone high-yield savings accounts, money market deposit accounts, or short-term certificates of deposit. To protect your savings strategy, obtain the bank's complete fee schedule and Truth in Savings disclosure before enrolling. Review those legal documents alongside official federal consumer guidance so you can make decisions based on binding account terms rather than software interface promises.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


